
The Treasury market’s month-long rally came to an abrupt end this week. A strong October payroll report last Friday along with a firmer-than-expected consumer price index (CPI) on Tuesday and an unusually coordinated hawkish message from Federal Reserve officials produced the steepest weekly rise in yields since April 2025. The 10-year note rose roughly 30 bps to 5.16% and the 30-year bond briefly touched 5.50% this morning. The 2-year yield posted its largest two-session rise since March 2023 between Tuesday and Thursday before retreating to ~4.85% this morning. Only a week earlier, the Democratic sweep in the midterm elections and renewed anxiety over the AI trade had drawn investors into Treasuries as a haven, but that positioning was largely unwound this week.
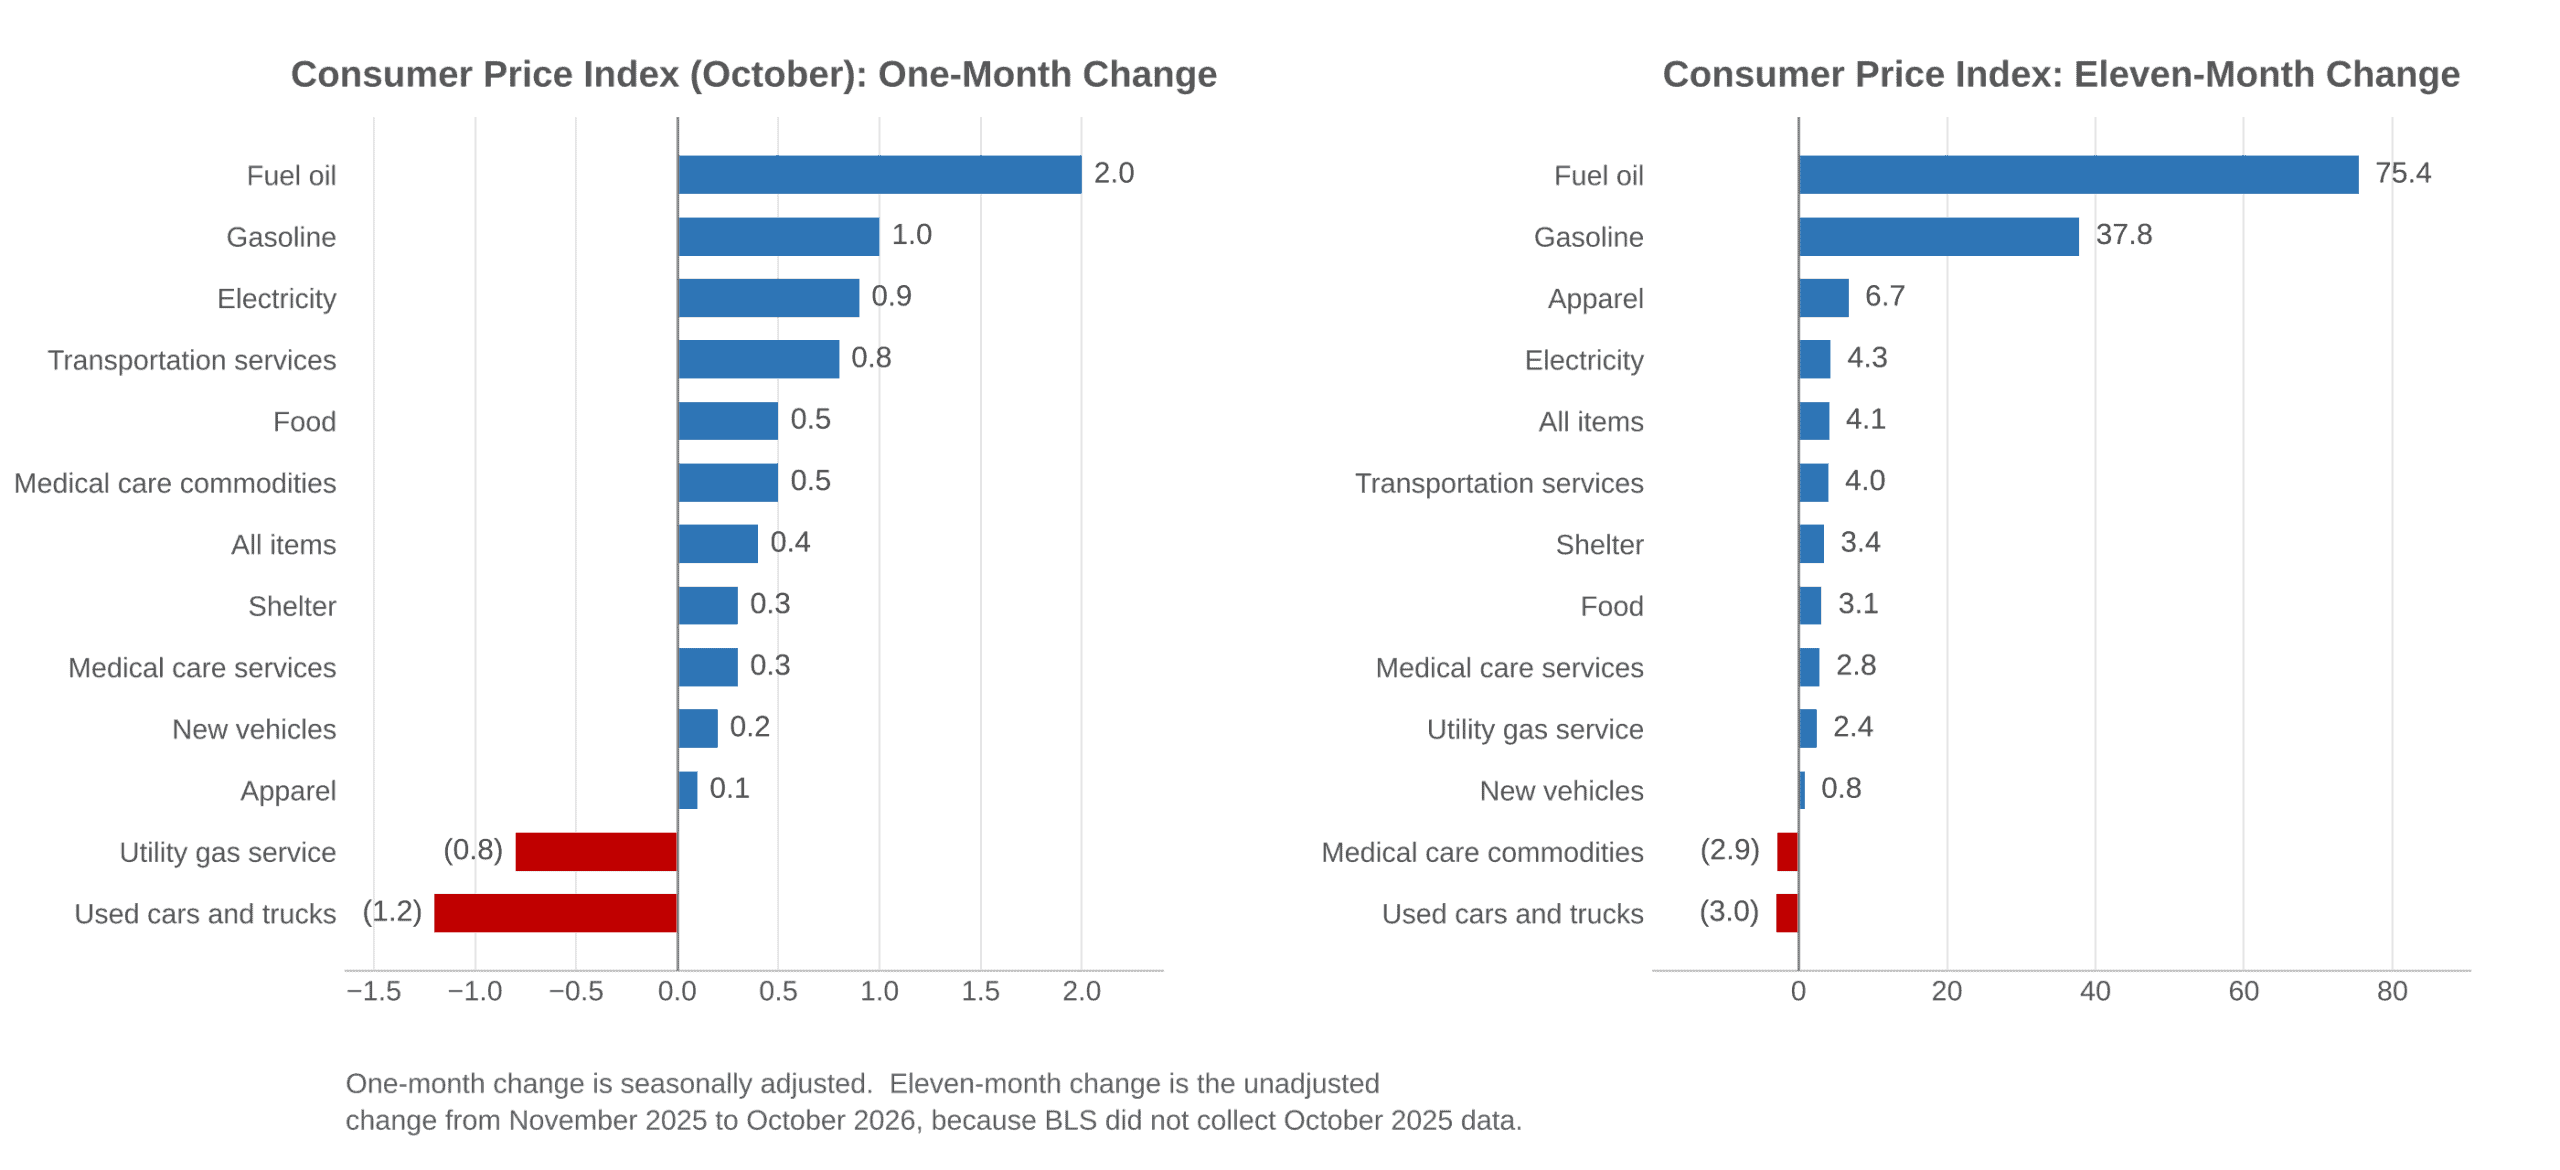
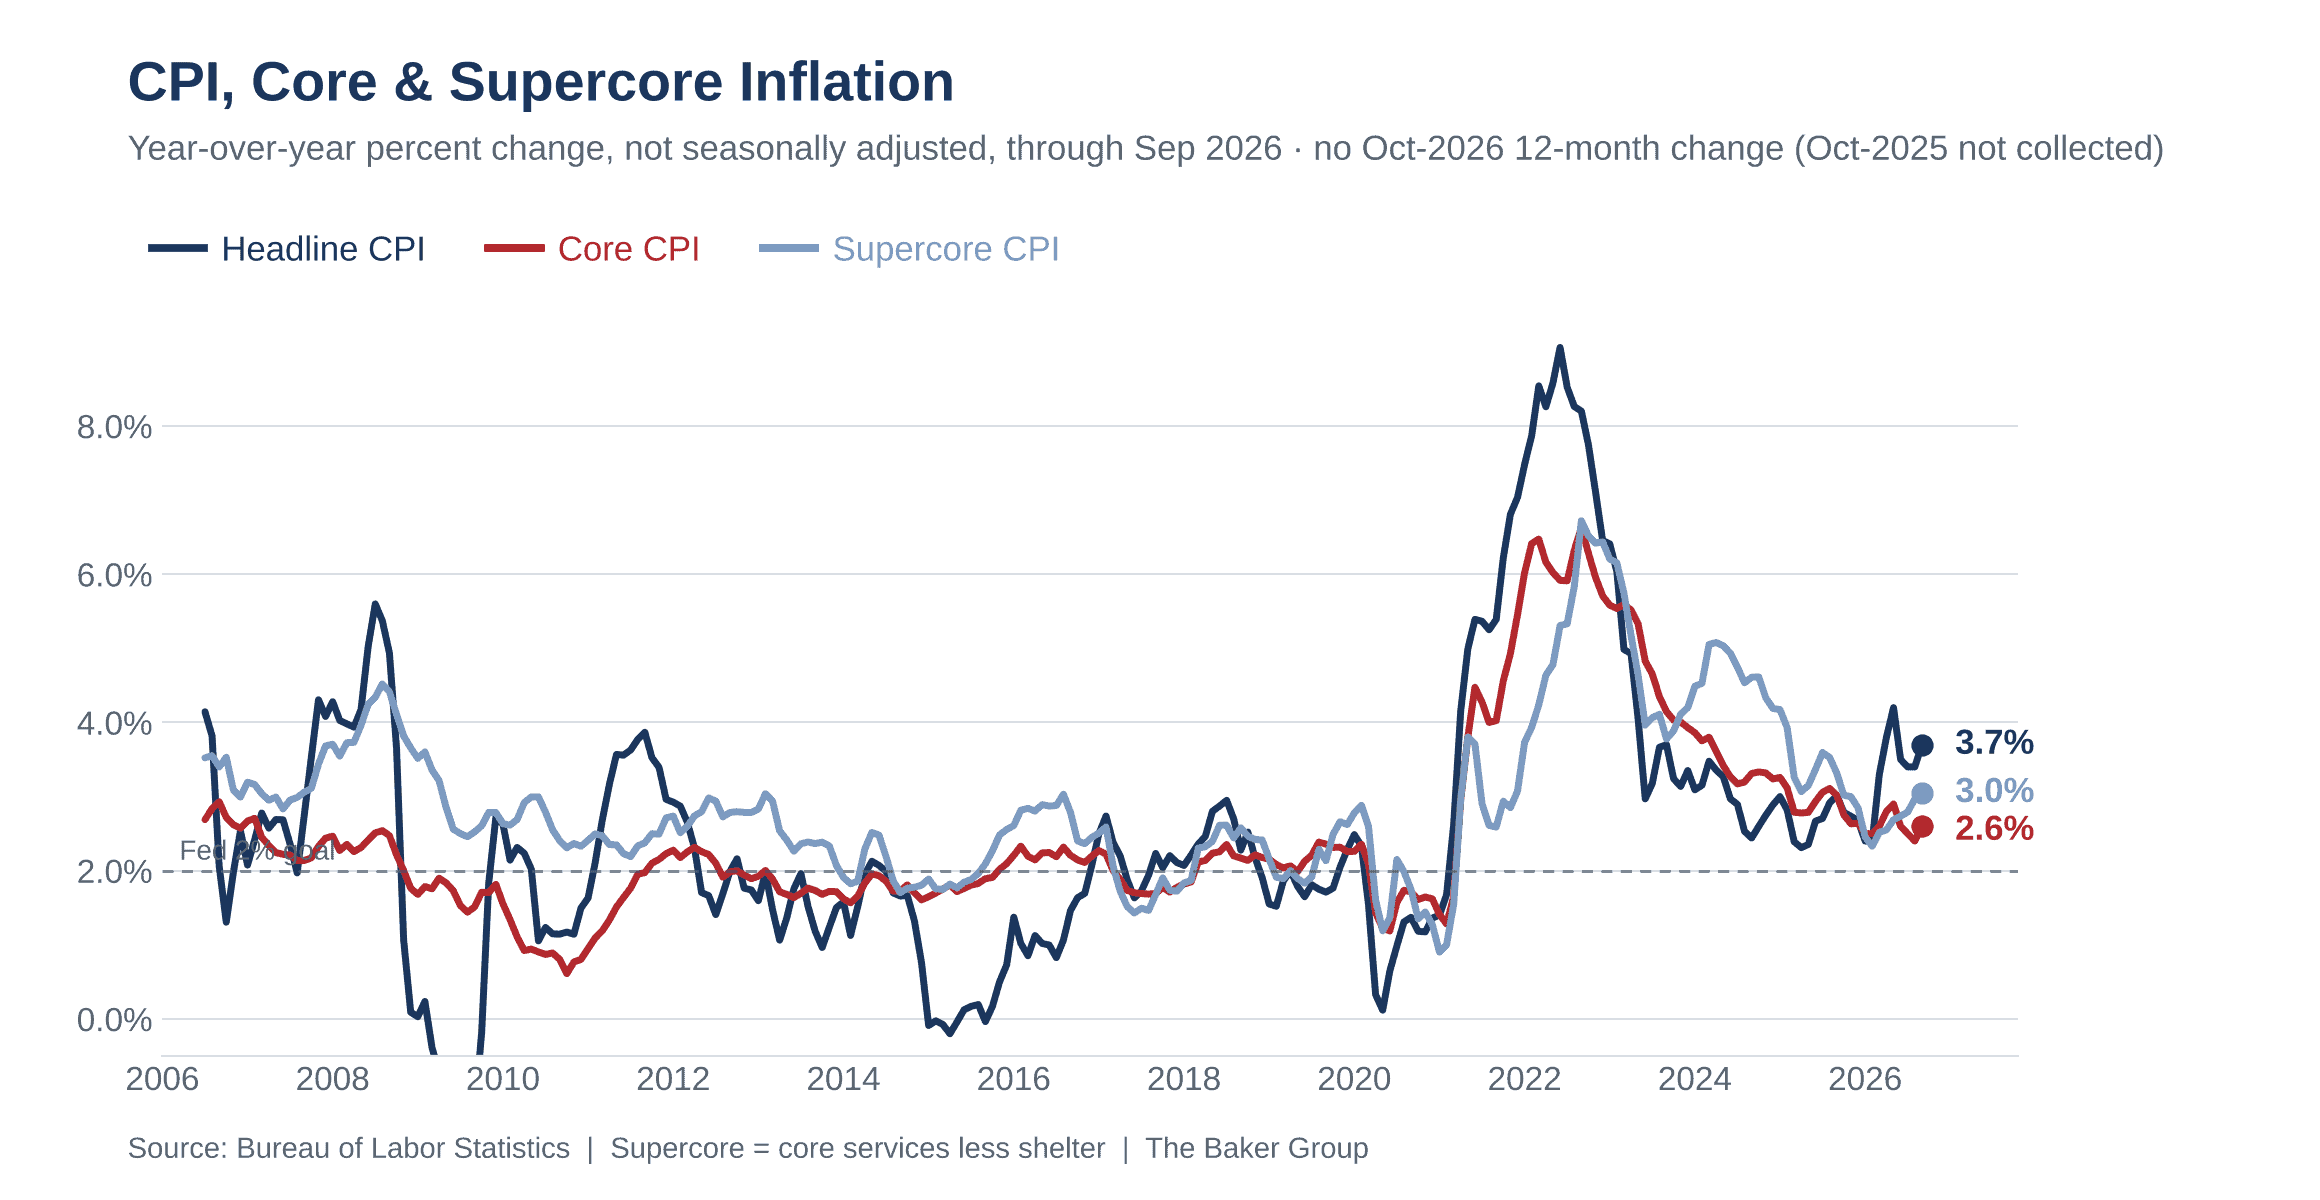
Tuesday’s CPI report showed headline consumer prices rose 0.4% in October, the third consecutive monthly gain of at least that size, and core prices rose 0.3%. No official year-over-year figure is available because of the data gap left by last year’s government shutdown, but economists estimate the headline annual rate at 3.9% to 4.0%. Friday’s producer price index was somewhat softer than expected at 0.3% for the month, although the 6.5% annual increase was the largest since November 2022.
Earlier on Tuesday morning, Fed Governor Christopher Waller, who was arguing for rate cuts less than a year ago, said the committee should consider a 50-basis-point hike in December if core inflation printed at 0.3% or higher. The CPI met that condition just hours later. Dallas Fed President Lorie Logan delivered a similar message, and New York Fed President John Williams said that inflation “is far too high” and that “we still have work to do.” Futures now fully price a 25 bp increase at the December 9 FOMC meeting, compared with roughly three-in-four odds a week ago, and suggest a ~10% chance of a half-point move.
The timing of this recent data is tricky. One of the year’s main inflation drivers could be reversing as President Trump said he is highly unlikely to resume strikes on Iran while negotiations continue. Brent crude is about 18% below its recent peak, near $96 a barrel this morning, but the October inflation data predates most of that decline. Even so, peace remains shaky. The naval blockade of the Strait of Hormuz is still in place and attacks on tankers continue. Skeptics of the hawkish turn argue that the Fed is responding with a blunt instrument to an imported supply shock. They point out that financial conditions have already tightened by an estimated 150 bps since February and that existing home sales fell 5.5% in October to a 16-year low. The 2s/10s spread has narrowed to below 30 bps, which leaves an inversion within reach if the Fed moves aggressively.
Next week’s calendar includes remarks from Chairman Warsh on Monday, October retail sales on Tuesday, minutes from the October FOMC meeting on Wednesday, and a possible meeting between Presidents Trump and Xi at the APEC summit in Shenzhen. Markets will read the minutes closely for any sign that the Fed regrets holding rates steady in October or that suggests a more aggressive move in December.
Have a great weekend!
The Baker Group is one of the nation’s largest independently owned securities firms specializing in investment portfolio management for community financial institutions.
Since 1979, we’ve helped our clients improve decision-making, manage interest rate risk, and maximize investment portfolio performance. Our proven approach of total resource integration utilizes software and products developed by Baker’s Software Solutions* combined with the firm’s investment experience and advice.
Author
Andrea F. Pringle
Senior Vice President
The Baker Group LP
800.937.2257
*The Baker Group LP is the sole authorized distributor for the products and services developed and provided by The Baker Group Software Solutions, Inc.
INTENDED FOR USE BY INSTITUTIONAL INVESTORS ONLY. Any data provided herein is for informational purposes only and is intended solely for the private use of the reader. Although information contained herein is believed to be from reliable sources, The Baker Group LP does not guarantee its completeness or accuracy. Opinions constitute our judgment and are subject to change without notice. The instruments and strategies discussed here may fluctuate in price or value and may not be suitable for all investors; any doubt should be discussed with a Baker representative. Past performance is not indicative of future results. Changes in rates may have an adverse effect on the value of investments. This material is not intended as an offer or solicitation for the purchase or sale of any financial instruments.