
Treasuries have rallied this week, pushing the 10yr yield back below 5%. We started the week at 5.12% on Monday and have fallen 16bp to 4.96% as of the time of this writing. The move largely reflects increased demand for safe-haven assets amid a broader risk-off tone, as AI stocks have led a sell-off in the equity market that has pushed the Nasdaq down around 15% from its October 6th high.
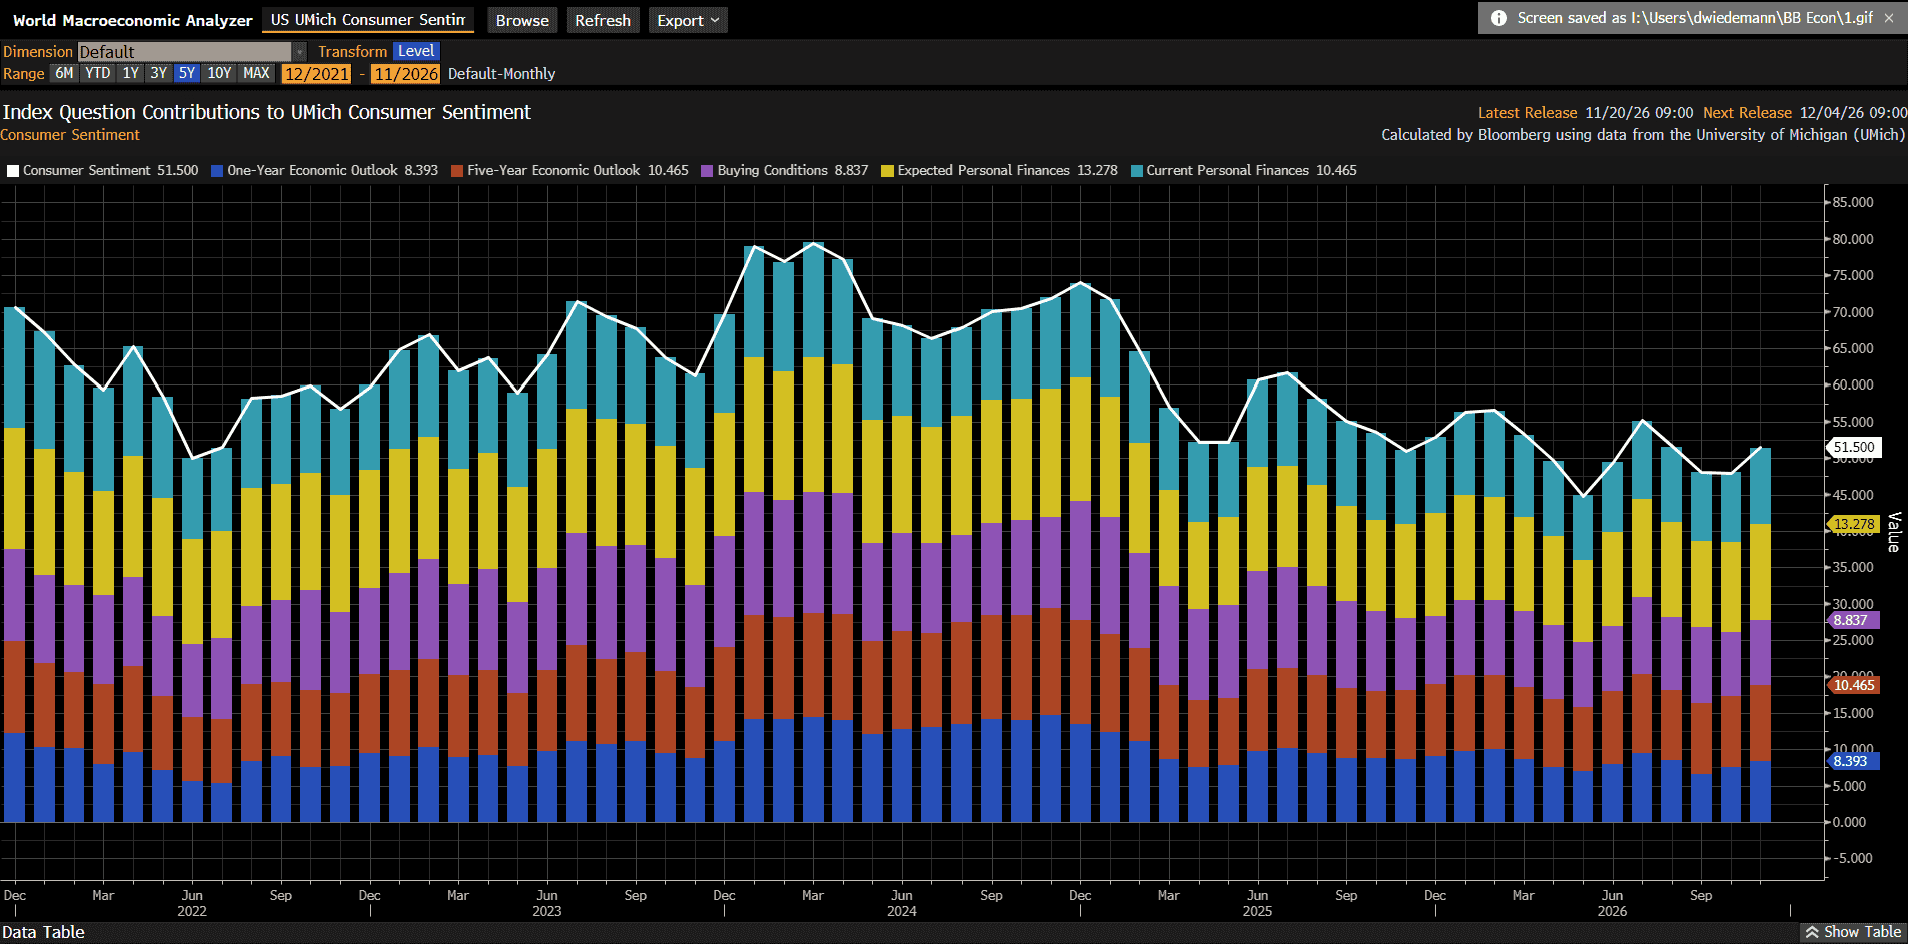
This week’s data showed a consumer that is still spending, while rate-sensitive parts of the economy continue to feel the strain of higher borrowing costs. Retail sales rose 0.2% in October (est = 0.1%), and the control group, which excludes volatile categories like autos and gas and feeds directly into GDP, rose 0.6% (est = 0.3%). Consumers are also feeling better, as the University of Michigan’s sentiment index rose to a three-month high of 51.5 from 48.0 in October. More importantly for the Fed, year-ahead inflation expectations fell to 3.7% from 4.7%, and long-run expectations eased to 3.3% from 3.5%. Regional manufacturing surveys were mixed, with New York and Philadelphia cooling sharply while Kansas City improved.
Housing remains the clearest casualty of higher rates. Builder sentiment fell to 25 (est = 29), building permits dropped 7.4% to 1.295mm (est = 1.375mm) and pending home sales fell 4.7% (est = -2.0%). Housing starts were the exception, rising 9.9% to 1.309mm (est = 1.250mm). The MBA 30-year mortgage rate climbed to 7.35% from 7.21%. The labor market also softened at the margin, with initial jobless claims rising to 203k (est = 198k) and continuing claims climbing to 1.76mm (est = 1.70mm). Even with the stronger retail sales, the weakness in industrial production and housing was enough to pull the Atlanta Fed’s GDPNow model, a real-time estimate of quarterly growth, down to 3.2% from 3.5% this week, though that still points to healthy growth in the fourth quarter.
On the Fed front, minutes from the October meeting showed that almost all participants expect further rate hikes will likely be appropriate, and a couple said a move larger than 25bp could be considered in December. Governor Waller went further on Wednesday, saying he favors a 50bp hike in December unless the Fed clearly signals another increase to follow. Markets are currently pricing in a 96% chance of a 25bp hike at the December meeting.
Next week is a holiday-shortened week, with markets closed Thursday for Thanksgiving, but it will still be busy, as we get a revised look at third quarter GDP along with October PCE on Wednesday. PCE, the Fed’s preferred inflation gauge, is expected to show core prices up 0.3% for the month and 3.2% from a year ago. This will be the last inflation reading the Fed will see before meeting in December.
Hope everyone has a great weekend!
The Baker Group is one of the nation’s largest independently owned securities firms specializing in investment portfolio management for community financial institutions.
Since 1979, we’ve helped our clients improve decision-making, manage interest rate risk, and maximize investment portfolio performance. Our proven approach of total resource integration utilizes software and products developed by Baker’s Software Solutions* combined with the firm’s investment experience and advice.
Author
Dillon Wiedemann
Senior Vice President of FSG
The Baker Group LP
800.937.2257
*The Baker Group LP is the sole authorized distributor for the products and services developed and provided by The Baker Group Software Solutions, Inc.
INTENDED FOR USE BY INSTITUTIONAL INVESTORS ONLY. Any data provided herein is for informational purposes only and is intended solely for the private use of the reader. Although information contained herein is believed to be from reliable sources, The Baker Group LP does not guarantee its completeness or accuracy. Opinions constitute our judgment and are subject to change without notice. The instruments and strategies discussed here may fluctuate in price or value and may not be suitable for all investors; any doubt should be discussed with a Baker representative. Past performance is not indicative of future results. Changes in rates may have an adverse effect on the value of investments. This material is not intended as an offer or solicitation for the purchase or sale of any financial instruments.