
Is it Friday already? It sure is, and this one closes the books on a week we have not seen in over three years. On Wednesday the FOMC raised the target range for fed funds a quarter point to 3.75%–4.00%. It is the first increase since July 2023, and the vote was unanimous, 12–0. Every community financial institution’s budgeting and planning assumption was that rates were headed lower in 2026. Instead, we get a 25 basis point hike with headline CPI at 3.4%, crude near triple digits, and a Chairman who doesn’t want to tell you what comes next.
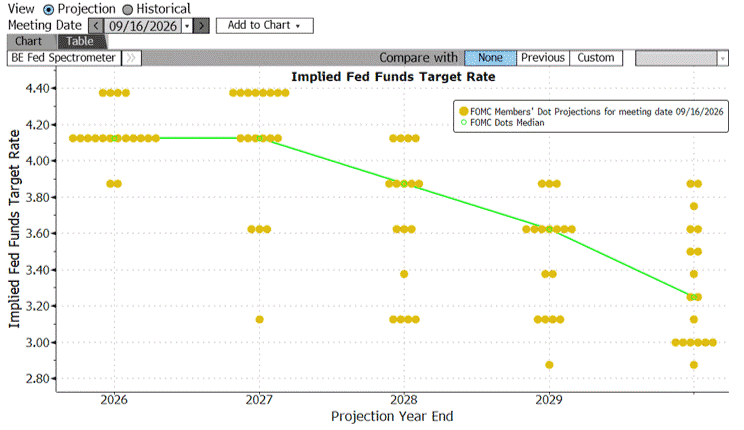
The quarter point hike was priced in and expected. The Summary of Economic Projections and the Dot Plot was a big question mark. The median fed funds projection jumped to 4.1% for both 2026 and 2027, from 3.8% and 3.6% in June, with 2028 at 3.9% and the longer run at 3.2%. The Committee marked GDP growth up to 2.3% and the unemployment rate down to 4.1%, and nudged 2026 PCE inflation to 3.7% with core at 3.4%.
The press conference was the shortest on record, and the Chairman spent most of his time explaining what he would not do. He framed the move as having “removed a dose of accommodation” rather than as the start of a campaign, and stated that “the plain fact is that inflation is too high and has been too high for too long.” On where policy stands today, he offered that he “would be hard-pressed to describe broad financial conditions as restrictive.” On what comes next: “I’m not in the forward guidance business.”
On Wednesday morning, August retail sales rose 1.2% month-over-month, well above the 0.7% expected and a solid rebound from July’s revised 0.5% decline. Before we credit the consumer too generously, gasoline stations did some of the lifting as pump prices climbed, though excluding gas stations sales still rose 1.1%. The average gallon of regular is now near $4.37.
Yesterday, the number of people applying for unemployment benefits dropped sharply, another sign that layoffs remain rare and we continue to be in a “low hire, low fire” labor market. The Labor Department reported Thursday that jobless claims slid to 196,000, the fewest since mid-July and down from 206,000 the week before. Expectations were for 207,500. The four-week average of claims, which smooths out week-to-week volatility, dropped to 203,250.
Stocks are down in early morning trading, with the 10-year Treasury near 5% and crude oil remaining over $100 per barrel.
Next week is a light week of economic data releases. On Thursday, we will get New Home Sales as well as the weekly jobless claims data. On Friday, we will receive the University of Michigan Consumer Survey.
Have a great weekend everyone!
September 2026 FOMC Dot Plot
The Baker Group is one of the nation’s largest independently owned securities firms specializing in investment portfolio management for community financial institutions.
Since 1979, we’ve helped our clients improve decision-making, manage interest rate risk, and maximize investment portfolio performance. Our proven approach of total resource integration utilizes software and products developed by Baker’s Software Solutions* combined with the firm’s investment experience and advice.
Author
Dale Sheller
Managing Director
Director of Financial Strategies Group
The Baker Group LP
800.937.2257
*The Baker Group LP is the sole authorized distributor for the products and services developed and provided by The Baker Group Software Solutions, Inc.
INTENDED FOR USE BY INSTITUTIONAL INVESTORS ONLY. Any data provided herein is for informational purposes only and is intended solely for the private use of the reader. Although information contained herein is believed to be from reliable sources, The Baker Group LP does not guarantee its completeness or accuracy. Opinions constitute our judgment and are subject to change without notice. The instruments and strategies discussed here may fluctuate in price or value and may not be suitable for all investors; any doubt should be discussed with a Baker representative. Past performance is not indicative of future results. Changes in rates may have an adverse effect on the value of investments. This material is not intended as an offer or solicitation for the purchase or sale of any financial instruments.