
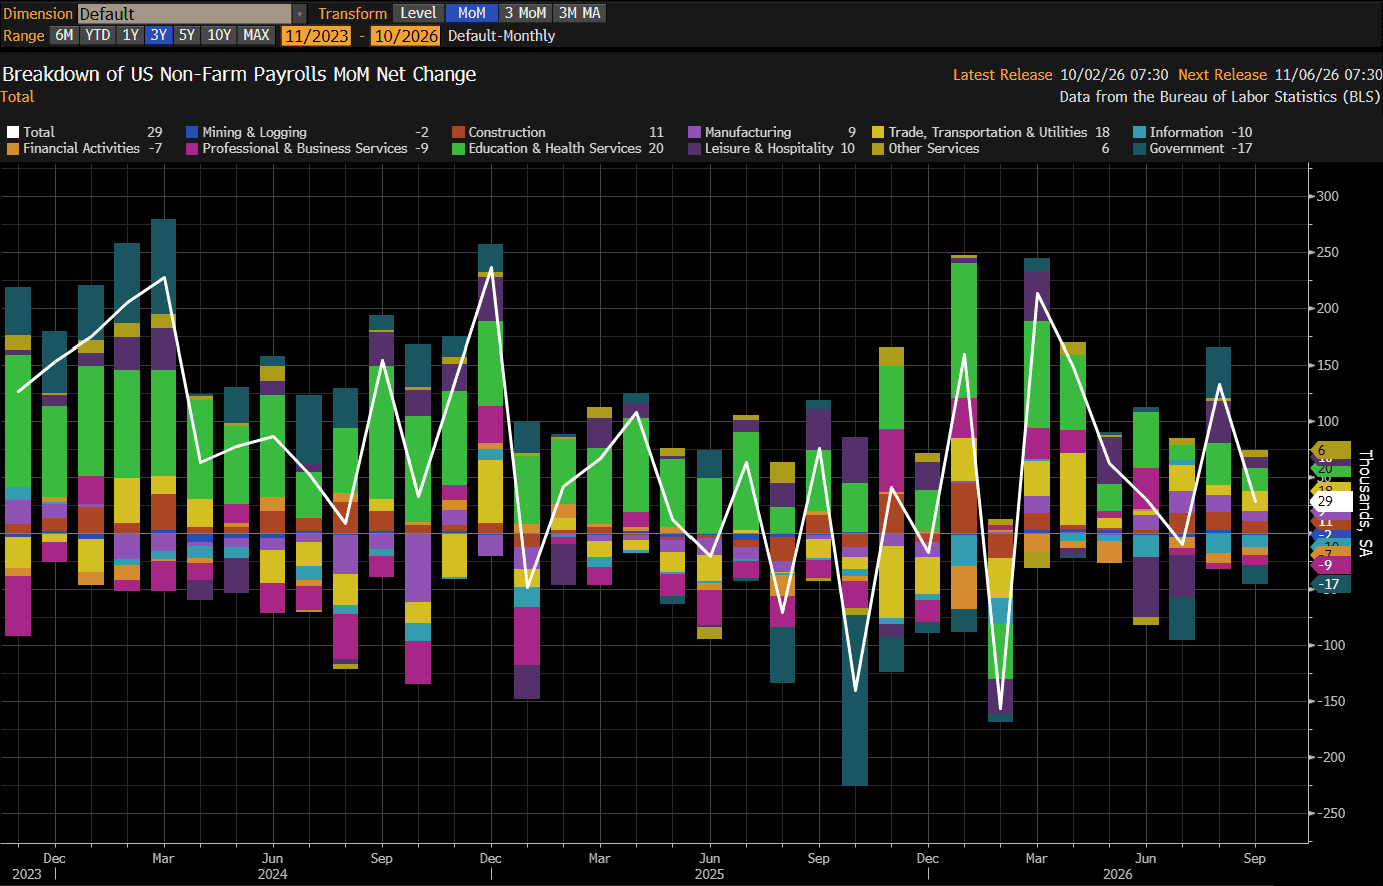
Treasury yields are lower this morning after September hiring fell well short of expectations and the prior two months were revised down. Employers added just 29k jobs in September (est = 90k), and revisions took another 60k off July and August. Health care and social assistance have added 520k jobs over the past twelve months, more than the 496k added by the economy as a whole, which means every other sector combined has shed jobs over the past year. The unemployment rate did move higher, but mostly due to people returning to the labor force. Add the slowest annual wage growth in more than five years, and the case for a second straight rate hike on October 28 looks considerably weaker. In fact, markets are now pricing in only a 20% chance of a rate hike later this month, down from 65% on Monday of this week.
July's originally reported gain is now a 10k loss and August was cut to 133k, which drops the three-month average to 51k from 71k. Private payrolls rose 46k (est = 81k). Health care, construction, and leisure and hospitality led the gains, while government, information, and professional services shed jobs. The household survey was stronger, showing employment up 406k. The unemployment rate rose to 4.2% (est = 4.1%) as the participation rate, the share of working-age adults either working or looking for work, climbed to 61.8% (est = 61.6%). Setting aside the 2020 reopening, the 0.4 point gain over the past two months is the largest since 1993. Wage growth cooled, with average hourly earnings up 0.1% for the month (est = 0.3%) and 3.0% from a year ago (est = 3.1%), the slowest annual pace since May 2021.
The rest of the week painted a mixed picture. Job openings slipped to 7.08mm in August (est = 7.23mm) while layoffs stayed low, which fits a labor market cooling through slower hiring rather than firings. Initial jobless claims held at 197k (est = 200k), but consumer confidence fell sharply to 81.9 (est = 89.0). Growth held up better as second quarter GDP was revised up to 2.2% (est = 1.5%), and August consumer spending rose 0.9%. ISM Manufacturing stayed in expansion at 54.5, but its prices paid index jumped to 77.9 (est = 73.0). The PCE price index, currently the Fed's preferred inflation gauge, rose 0.3% in August (est = 0.3%), and core PCE rose 0.2% (est = 0.3%), slightly better than expected. From a year ago, headline PCE was up 3.4% and core was up 3.0%, both unchanged from July.
Bond yields fell sharply on the release but have since given back much of that move. As of the time of this writing, the 2yr yield was down about 1bp to 4.78% and the 10yr was down about 3bp to 5.21%. Attention now turns to September CPI on October 14 and PPI on October 15, the last inflation data the Fed will see before its October 28th meeting. With input prices rising sharply, those reports will go a long way toward deciding whether a softening labor market is enough to keep the Fed on hold. Hope everyone has a great weekend!
The Baker Group is one of the nation’s largest independently owned securities firms specializing in investment portfolio management for community financial institutions.
Since 1979, we’ve helped our clients improve decision-making, manage interest rate risk, and maximize investment portfolio performance. Our proven approach of total resource integration utilizes software and products developed by Baker’s Software Solutions* combined with the firm’s investment experience and advice.
Author
Dillon Wiedemann
Senior Vice President of FSG
The Baker Group LP
800.937.2257
*The Baker Group LP is the sole authorized distributor for the products and services developed and provided by The Baker Group Software Solutions, Inc.
INTENDED FOR USE BY INSTITUTIONAL INVESTORS ONLY. Any data provided herein is for informational purposes only and is intended solely for the private use of the reader. Although information contained herein is believed to be from reliable sources, The Baker Group LP does not guarantee its completeness or accuracy. Opinions constitute our judgment and are subject to change without notice. The instruments and strategies discussed here may fluctuate in price or value and may not be suitable for all investors; any doubt should be discussed with a Baker representative. Past performance is not indicative of future results. Changes in rates may have an adverse effect on the value of investments. This material is not intended as an offer or solicitation for the purchase or sale of any financial instruments.