It’s Halloween week, and the stock market appears to be spooked this morning, with tech stocks leading a selloff. The QQQ ETF, which holds a basket of large technology stocks, has fallen about 8.5% since October 6th. Over the same period, the 10yr Treasury yield has rallied about 32bp, from 5.27% to 4.95% (as of the time of this writing). Some of that decline reflects a flight to quality as investors trim risk, though softer labor data and fading expectations for a near-term rate hike have also played a role. The biggest news of the week was that the Fed held rates steady at its October meeting. The FOMC voted 10-2 to maintain the target range at 3.75% to 4.00%, with Governor Cook and Cleveland Fed President Hammack dissenting in favor of another 25bp hike. Chairman Warsh described the period ahead of the December 9 meeting as “information rich,” signaling that the Committee wants to see more data before deciding its next move. He also noted that financial conditions have tightened since September’s hike, which he views as a sign that policy is working. With inflation still well above target and Warsh offering no guidance on December, markets continue to lean toward a hike at that meeting.
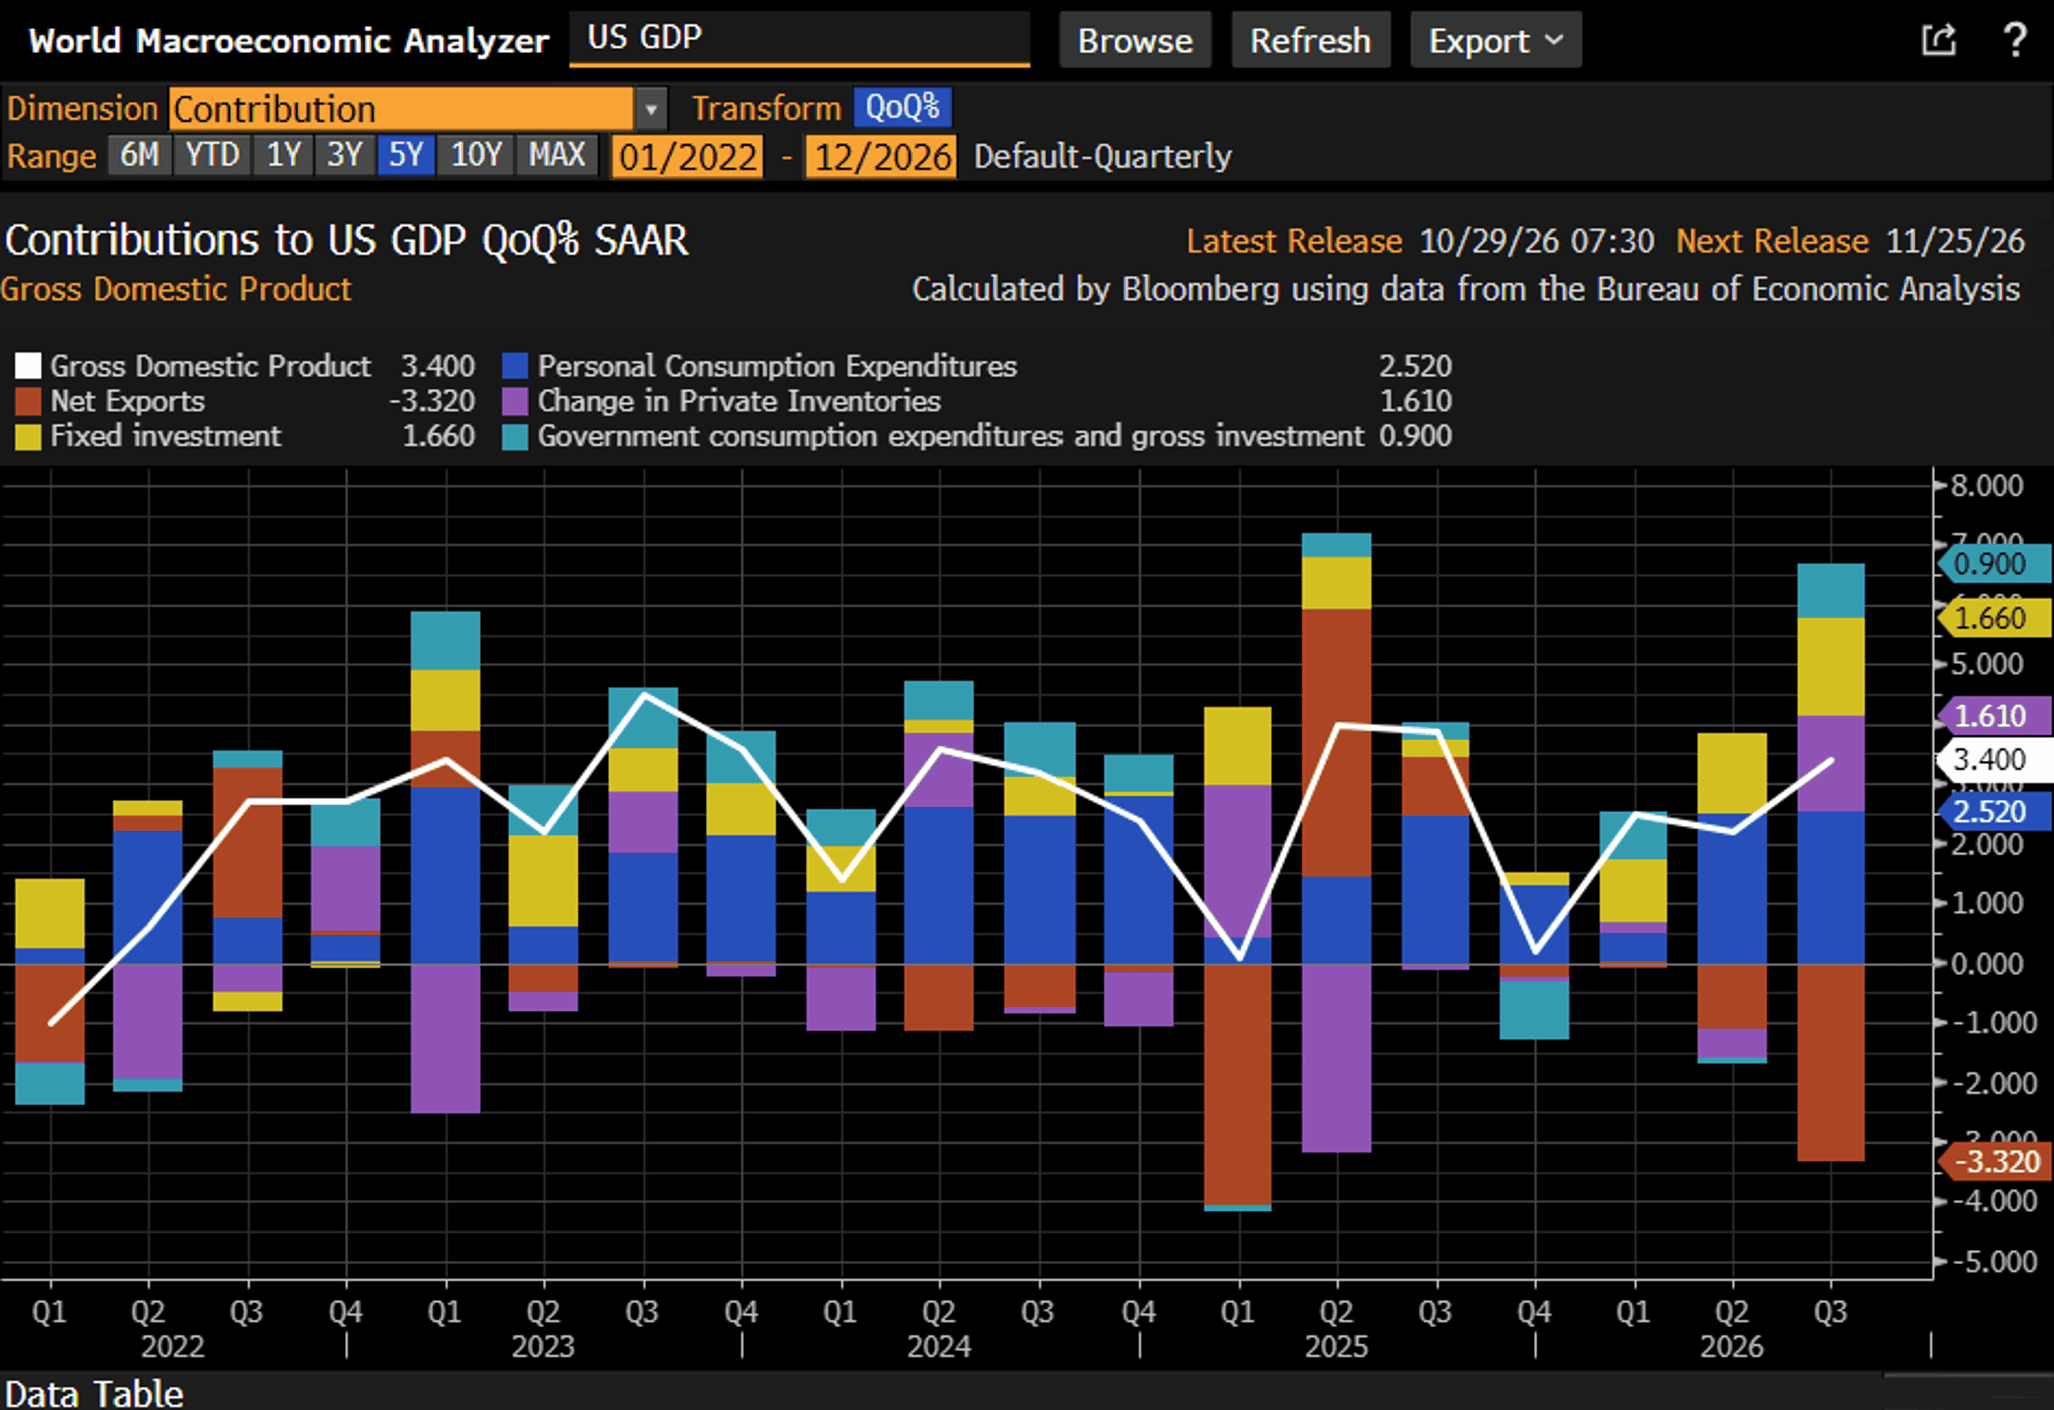
The data released after the meeting did little to change that view. The economy grew at a 3.4% annualized rate in the third quarter (est = 3.2%), led by consumer spending, which rose 3.8% (est = 3.4%). The quarterly inflation readings were more encouraging, with the GDP price index slowing to 2.3% (est = 3.2%) from 6.1% in the second quarter and core PCE prices rising at a 2.5% annualized pace (est = 2.4%).
The monthly inflation figures were less friendly. The PCE price index, the Fed’s preferred inflation gauge, rose 0.5% in September (est = 0.5%) and 3.6% from a year ago (est = 3.6%), up from 3.4% in August. Core PCE, which excludes food and energy, rose 0.3% (est = 0.3%) and 3.1% from a year ago (est = 3.1%), up from 3.0%. Personal income rose 0.2% (est = 0.3%) and spending rose 0.5% (est = 0.6%), which left inflation-adjusted spending flat for the month.
Elsewhere, consumers appear to be regaining some confidence. The Conference Board’s index jumped to 91.7 (est = 81.0) from 84.2, with both the present situation and expectations components rising sharply. New home sales came in at 676k (est = 651k), and durable goods orders rose 1.8% (est = 1.9%). Capital goods orders Nondefense Ex-Air, a proxy for business investment, rose 0.5% (est = 0.7%). All in all, this week’s data points to an economy on solid footing with sticky inflation, a combination that keeps a December rate hike on the table.
The Fed’s next big test will come next week when we get employment numbers for October. Also, don’t be surprised to see market volatility continue into next week with midterms.
Hope everyone has a great weekend!
The Baker Group is one of the nation’s largest independently owned securities firms specializing in investment portfolio management for community financial institutions.
Since 1979, we’ve helped our clients improve decision-making, manage interest rate risk, and maximize investment portfolio performance. Our proven approach of total resource integration utilizes software and products developed by Baker’s Software Solutions* combined with the firm’s investment experience and advice.
Author
Dillon Wiedemann
Senior Vice President of FSG
The Baker Group LP
800.937.2257
*The Baker Group LP is the sole authorized distributor for the products and services developed and provided by The Baker Group Software Solutions, Inc.
INTENDED FOR USE BY INSTITUTIONAL INVESTORS ONLY. Any data provided herein is for informational purposes only and is intended solely for the private use of the reader. Although information contained herein is believed to be from reliable sources, The Baker Group LP does not guarantee its completeness or accuracy. Opinions constitute our judgment and are subject to change without notice. The instruments and strategies discussed here may fluctuate in price or value and may not be suitable for all investors; any doubt should be discussed with a Baker representative. Past performance is not indicative of future results. Changes in rates may have an adverse effect on the value of investments. This material is not intended as an offer or solicitation for the purchase or sale of any financial instruments.